An audit committee oversees financial reporting without replacing management
An audit committee scrutinises financial reporting but does not replace management’s preparation work. Learn where to look for its responsibilities and judgments.
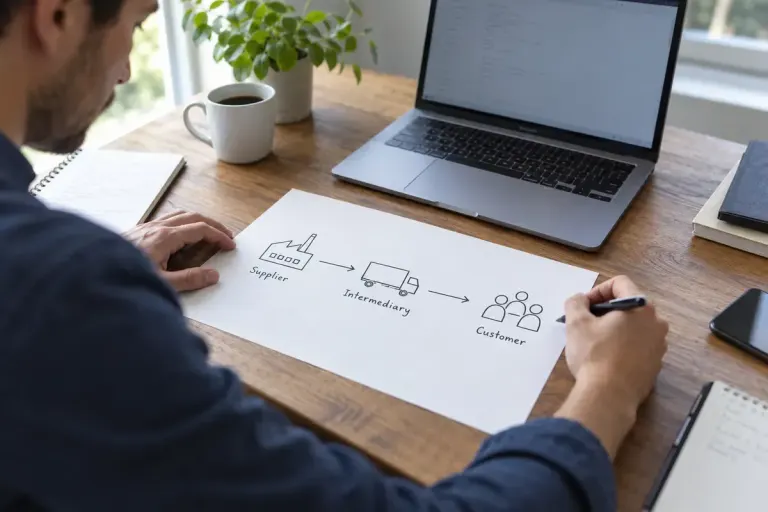
An audit committee scrutinises financial reporting but does not replace management’s preparation work. Learn where to look for its responsibilities and judgments.
Revenue may be reported gross or as a fee depending on whether a company acts as principal or agent. Follow the promised service before comparing totals.

A dormant UK limited company can still need accounts and a confirmation statement. Check the relevant definition and deadlines rather than equating no trading with no duties.

Read an inventory write-down as a valuation change, then check the company’s explanation before assuming the stock was sold or discarded.

A material weakness concerns the reliability of financial-reporting controls. Read the affected process, assessment date and remediation status before drawing conclusions.

Acquisition goodwill is an accounting amount, not a customer-satisfaction score. Read the business-combination note to understand where the figure comes from.

Read subsequent-event disclosures by separating evidence about conditions at the reporting date from significant developments that arose afterwards.

Work can belong to an accounting period before its invoice arrives. An accrual records that obligation, with evidence and a clear reconciliation later.

Understand prepaid expenses through a simple insurance example and distinguish the cash payment from the cost recognised in each accounting period.