Company Operations
A company handover needs a list of contracts that renew automatically
Include automatic-renewal contracts in a company handover, with verified notice deadlines, responsible owners and access to the governing documents.

Business models, operations and the decisions behind them.
Include automatic-renewal contracts in a company handover, with verified notice deadlines, responsible owners and access to the governing documents.
Separate permission to sign a document from internal approval of its cost, scope and ongoing commitments in a company’s purchasing workflow.
Compare operating profit and EBITDA by reading the company’s definitions and reconciliation, rather than assuming they measure the same costs or cash generation.
Check the ageing basis and report date before treating a receivable as overdue, then reconcile payments, credits and disputes before following up.
Read group-company relationships through control and significant influence, and distinguish consolidated subsidiaries from associates in IFRS reporting.
An accounting provision recognises an uncertain liability. It does not necessarily mean the company has placed an equal amount of cash in a separate account.
Depreciation allocates an asset’s depreciable cost over its useful life. A simple example separates accounting expense from the original cash payment.
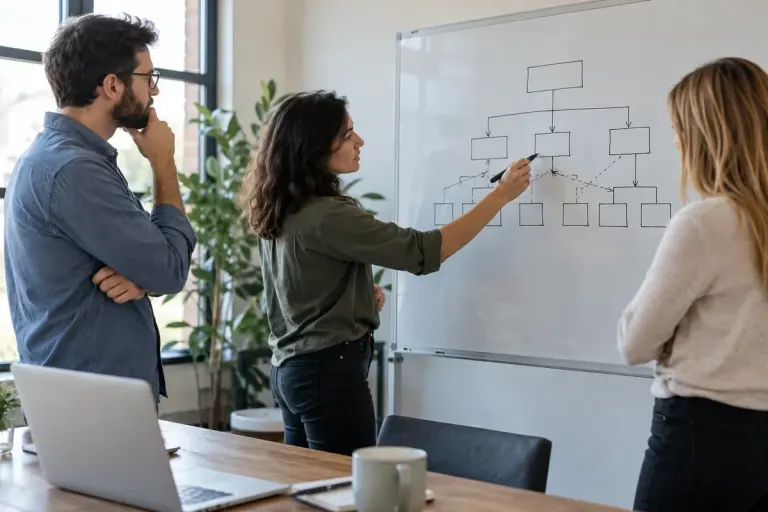
Read a matrix organisation chart by asking who sets priorities, reviews work and resolves conflicts between reporting lines.
A public-facing trading name can differ from the legal entity on a contract. Check the registered identity before recording a supplier or customer.