
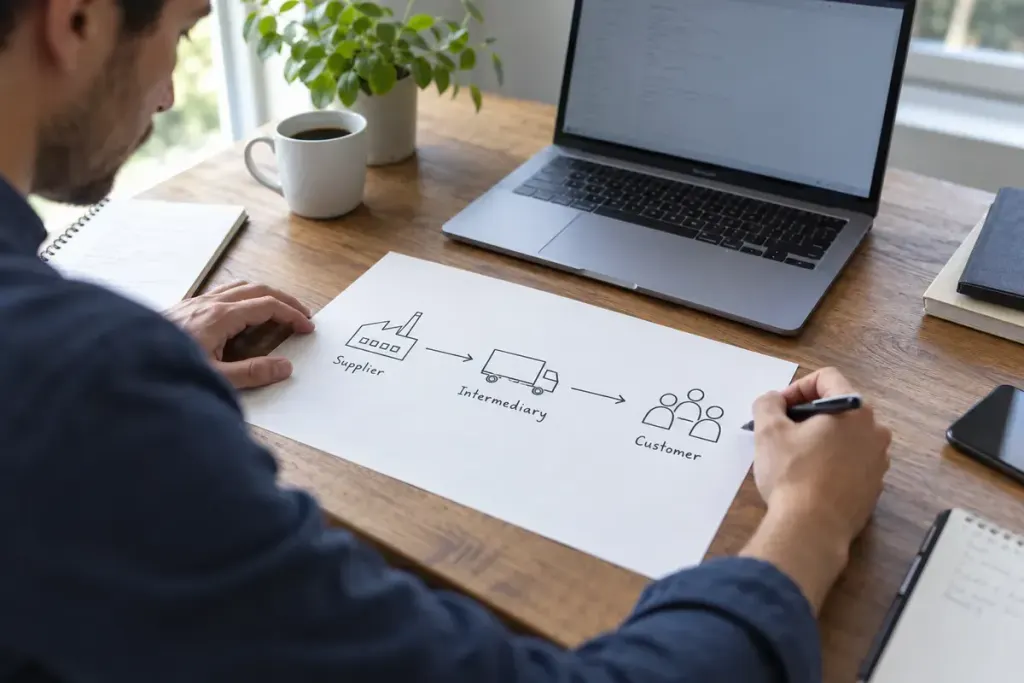
Two companies can handle customer transactions of similar value and report very different revenue. One may provide the goods or services itself as principal; another may arrange for a different party to provide them and earn a fee as agent.
Under IFRS 15, the central assessment concerns control of the specified good or service before it is transferred to the customer. The IFRS Foundation’s summary of the principal-versus-agent requirements explains the resulting distinction between gross revenue and the fee or commission recognised by an agent.
Follow a fictional transaction
Imagine a customer pays 100 units through an intermediary, which retains 15 and passes 85 to a supplier. The cash movement alone does not establish the accounting conclusion.
If the intermediary is an agent for that specified service, its revenue may be the 15-unit fee. If it is principal, the relevant gross consideration may be revenue, with costs accounted for separately. This simplified example excludes tax and other contractual details and is not an accounting treatment for a real business.
Ask what the company promised the customer and whether it controlled the promised service before transfer. Responsibility for fulfilment, inventory risk and pricing discretion can provide evidence, but they should not be turned into a mechanical checklist where one tick decides every case.
A company may also be principal for one part of an arrangement and agent for another. A label such as “platform”, “marketplace” or “reseller” does not settle the analysis.
Read comparisons with care
When comparing companies, inspect the revenue-recognition policy and any discussion of gross transaction value or similar operating metrics. A large transaction-volume figure should not be silently compared with another company’s recognised revenue.
Likewise, a change from gross to net presentation can affect revenue and margin percentages without representing the same change in underlying customer activity. Read the explanation and comparative information before attributing the movement to growth or decline.
For an actual reporting decision, the contract and applicable accounting framework need professional assessment. For a reader of accounts, the first useful habit is simpler: find out what the company did in the sale before interpreting the size of its revenue.