
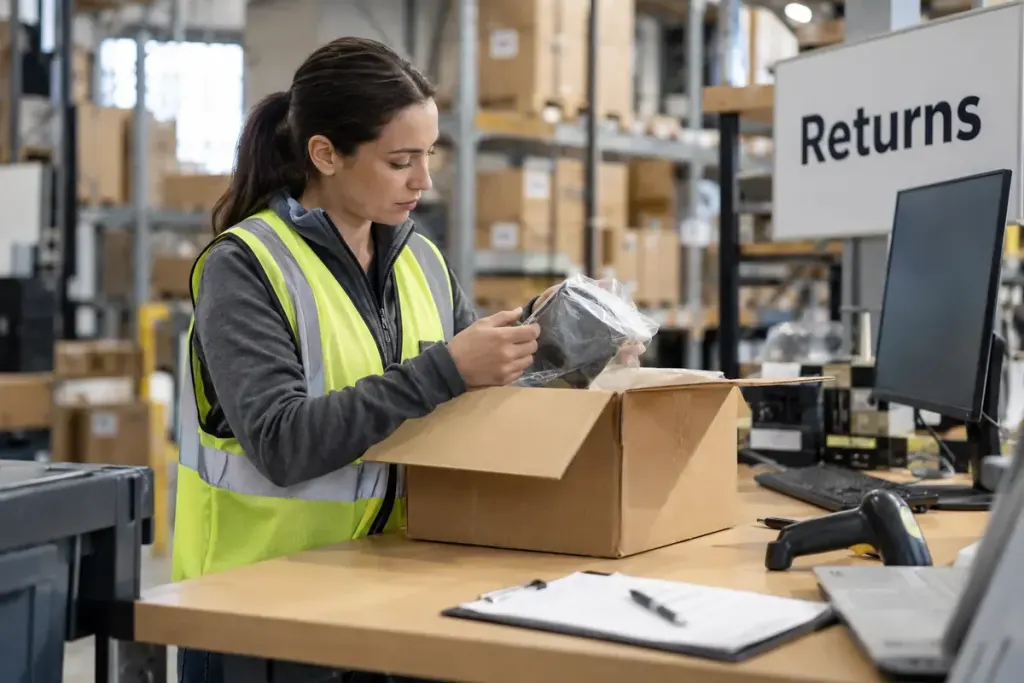
A refund has been approved, the customer has sent the item back, and the parcel is sitting near the stockroom door. Financially, the return may look complete. Operationally, someone still needs to decide what the business now owns and whether it can be sold again.
Give the return an identity
Connect the parcel to a return reference, the original order and the expected item. Record the quantity received and any identifying information appropriate to the product, such as a serial or batch number. A customer saying “the blue one” is not enough for a stock adjustment when several similar products exist.
Keep the return separate from saleable stock until the required inspection is complete. Receiving an item and approving it for resale are different events. The person handling the refund may not be the person qualified to assess the product.
Use meaningful stock states
- Received and awaiting inspection.
- Approved for return to saleable stock.
- Assigned to repair, supplier review or another authorised process.
- Rejected for resale and awaiting an approved disposition.
Adapt those states to the business and product rules. Food, medical products, safety equipment and other regulated goods can have restrictions that ordinary retail examples do not cover. Do not make “looks unopened” the default approval test.
Close the loop with the records
Record who made the disposition decision and when. Link any replacement shipment, credit or supplier claim so different teams do not process the same remedy twice. If a quantity differs from the expected return, resolve the discrepancy before changing available stock.
A useful weekly review asks which returns are still waiting and why. Repeated delays may reveal missing product information, unclear authority or insufficient inspection capacity. The aim is not merely to empty a shelf of returned parcels; it is to make the inventory record reflect what can actually be supplied to the next customer.